Savings, credit, investments are next frontiers – MMFL
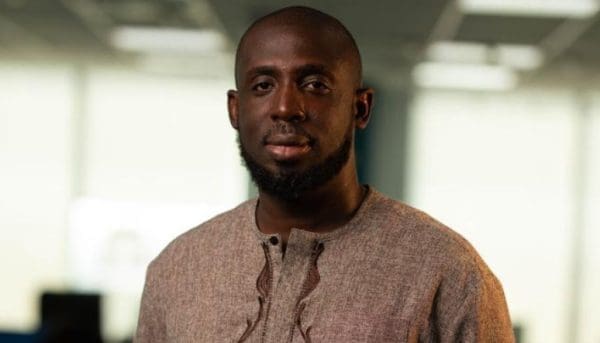
Abdul-Razak Issaka Ali, Chief Commercial Operations Officer of MMFL
The next phase of financial inclusion in Ghana must move beyond basic money transfers and give more people access to savings, investments, credit, insurance and other services that can help them build stronger financial futures, the Chief Commercial Operations Officer of MobileMoney FinTech Limited (MMFL), Abdul-Razak Issaka Ali, has said.
He said the growing use of mobile money had created a strong foundation for financial inclusion, but the real opportunity now was to convert widespread access into meaningful financial value and improved financial health for customers.
Mr Ali made the call at the launch of MTN Ghana’s 2026 DigiFest, where he outlined the changing role of digital finance in Ghana’s financial ecosystem.
He said while mobile money had been created primarily to make it easier for people to move money and extend financial services to underserved populations, customers could now use the platforms to access a much wider range of financial products.
“MoMo was created to meet a customer need: to make it easier to move money and extend financial inclusion to every Ghanaian. The opportunity now is to help customers do much more with that access,” he said.
Beyond transactions
Mr Ali noted that many customers continued to use their mobile money wallets mainly for sending and receiving money and storing funds, leaving significant room to expand their use of digital platforms for savings, credit, investments, insurance and pensions.
He said financial inclusion should therefore not be measured solely by whether an individual could complete a digital transaction.
“Financial inclusion should not end with being able to make a transaction. It should open the door to products that help people manage risk, plan for the future and pursue new opportunities,” he said.
According to him, the next stage of digital finance should focus on helping customers make better financial decisions and access products that respond to their changing needs.
That, he said, would transform digital finance from a transactional tool into an important instrument for improving household financial resilience and economic opportunity.
Partnership critical
Mr Ali stressed that achieving a more financially inclusive and cash-lite economy would require sustained collaboration among mobile money operators, banks, insurance companies, pension providers, fintech companies, regulators and other players in the financial-services ecosystem.
“A cash-lite economy cannot be delivered by MoMo alone. It must be built in partnership with the institutions and innovators that together serve the financial needs of Ghanaians,” he said.
He said MMFL’s platform-based approach was intended to allow partners to make a broader range of financial products available to customers.
The MoMo App, he added, provided a single and convenient channel through which customers could discover, access and manage multiple financial and lifestyle services.
This approach, he said, could make financial services more accessible while reducing the difficulty customers face in navigating different products and providers.
AI, APIs to drive innovation
Mr Ali also identified artificial intelligence (AI) and application programming interfaces (APIs) as important technologies for the next phase of digital financial services.
He said the technologies could help financial institutions personalise services, integrate products more efficiently and respond more quickly to customer needs.
They could also strengthen fraud detection and prevention, which he identified as essential to building confidence in digital financial services.
He said technology should, however, be deployed with a clear focus on customer outcomes rather than innovation for its own sake.
Fintech innovation
As part of its efforts to support homegrown innovation, MMFL is implementing the MoMo FinTech Lab, an innovation and development programme designed to identify and support promising fintech ideas with the potential to shape Ghana’s financial-services industry.
The programme provides selected participants with mentorship, skills development, technical support, stakeholder engagement, networking and pitching opportunities.
The initiative is intended to help innovators develop practical solutions while connecting promising ideas with the broader financial-services ecosystem.
Mr Ali said the success of digital finance would ultimately depend on whether innovation translated into tangible improvements in the lives of customers.
“The goal is not technology for its own sake. It is to use technology and partnerships to solve real customer needs, expand opportunity and help more Ghanaians build healthier financial lives,” he said.