Ghana’s rural banking sector hits GH¢26 billion milestone
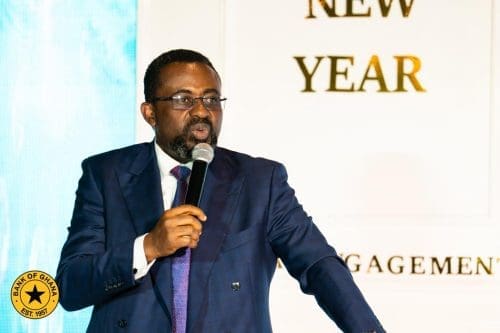
Dr Johnson Asiama
Ghana’s rural banking sector has grown into a GH¢26 billion industry, with 147 licensed institutions serving more than 8 million customers as of May 2026, Bank of Ghana Governor Dr Johnson Asiama has announced.
Dr Asiama said the growth reflected the success of the country’s rural banking model, which was introduced 50 years ago to bring formal financial services closer to underserved communities.
Speaking at a special event marking the golden jubilee of this transformative initiative, the Governor painted a picture of remarkable progress rooted in a simple but powerful vision of financial inclusion for all Ghanaians, particularly those in rural areas who had long been excluded from mainstream banking.
“What began with one bank at Nyakrom is today 147 licensed institutions, about 1,000 branches, more than 8 million customers, and an asset base of approximately GH¢26 billion as of May this year,” the Governor said.
He was speaking at an event to commemorate the 50th anniversary of Ghana’s Rural Banking Programme on Thursday, July 16, 2026. The celebration not only honoured past achievements but also served as a platform to reflect on the programme’s impact on national development and to chart a path forward.
According to him, the figures represented more than institutional growth, describing them as evidence that the original vision behind rural banking had delivered results.
“They are not a measure of institutional success. They are a verdict on the original idea,” Dr Asiama said.
The Governor traced the origins of the programme to 1976, when the Nyakrom Rural Bank in the Central Region became the first community-owned bank established in Ghana. At the time, the country’s formal banking system was largely concentrated in urban centres, leaving vast segments of the population—especially farmers, small-scale traders, artisans, and rural households—without access to basic financial services.
Traditional banks often viewed these communities as high-risk or unprofitable, creating a significant gap in economic participation.
The rural banking model was designed to bridge this divide by establishing locally owned and managed financial institutions that understood the unique needs, rhythms, and realities of rural economies. It empowered communities to take ownership of their financial destiny, fostering a sense of pride and responsibility.
“People saved. People borrowed. People built. They simply did it without a bank because there was no appropriate bank for them to do it with,” he said.
Over the past five decades, rural banks have played a pivotal role in financing agriculture—the backbone of Ghana’s economy—by providing credit for crop production, livestock rearing, and agro-processing. They have supported small and medium-sized enterprises, facilitated the mobilisation of savings from even the most modest earners, and gradually integrated rural populations into the broader formal financial system. This has contributed to poverty reduction, improved livelihoods, and stimulated local economic activities across the country.
However, the journey has not been without difficulties. Dr Asiama acknowledged that the sector had faced challenges, including governance weaknesses and institutional failures, which affected public confidence in some communities.
Such setbacks highlighted the vulnerabilities inherent in community-driven financial models, where mismanagement could have deeply personal and communal repercussions.
“When one failed, the loss was not recorded in a supervisory return and was forgotten. It was recorded in a community, in its savings, in its confidence, and in the faith it had placed in an institution carrying its own name,” he said.
In response, the Bank of Ghana has implemented ongoing reforms to strengthen the sector while preserving its original purpose of financial inclusion. These reforms include transitioning rural banks into community banks and expanding the model beyond rural areas to allow community banking in urban centres. The goal is to create a more resilient framework that combines local participation with stronger regulatory oversight, risk management, and capacity building.
Dr Asiama emphasised that the sustainability and future success of community banking would hinge on core principles that defined its early years. He called for continued emphasis on trust, accountability, active community participation, and a focus on local development initiatives.
“These are the values that must carry it again for the next 50 years,” he said.
As Ghana commemorates this significant milestone, the rural banking programme stands as a testament to the power of inclusive financial policies. With its impressive growth statistics and renewed reform agenda, the sector is well-positioned to play an even greater role in driving equitable economic development, empowering communities, and contributing to the nation’s long-term prosperity.
The next half-century offers an opportunity to build on this strong foundation, ensuring that formal banking remains accessible, responsive, and rooted in the communities it serves.